CoverMe - Instant Cash Advance

Screenshots
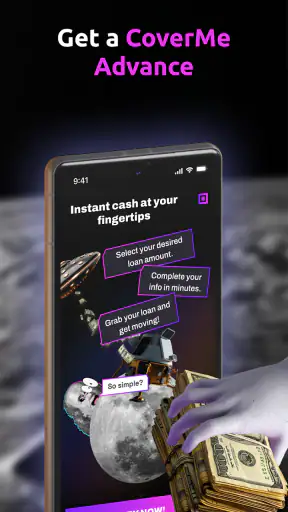
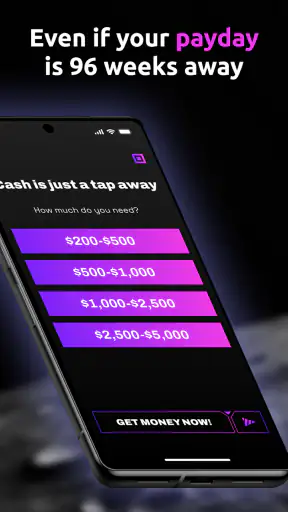
Details
- Rating
- 2.10K reviews
- Version
- 1.6.3
- Developer
- DIONIS K
Analysis by Norviv
I came away from CoverMe with a clear impression: it is designed to make short-term access to cash feel less tied to the traditional payday cycle. That is an appealing idea when an unexpected bill arrives before the next paycheck, but it also demands careful judgment. An app that helps bridge a gap can be useful; it should not become a routine substitute for a workable monthly budget.
This is a free finance app from DIONIS K, and its central promise is access to cash even when payday is far away. The app is aimed at people who need to examine an advance option quickly rather than compare a long list of conventional lending products. I found that focus both helpful and limiting: the narrow purpose keeps the experience easy to understand, while the financial decision itself still requires more attention than a few taps.
The public response is encouraging, with a 4.6 average from around 32 thousand ratings and more than 100 thousand installs. It is rated for Everyone, which makes the app broadly approachable from an age-classification standpoint, but that should not be confused with suitability for every financial situation. A simple interface can make borrowing feel harmless when repayment still affects the rest of the month.
How CoverMe works as a short-term money tool
I’d treat CoverMe as a way to examine a short-term cash option, not as money already available to spend. Before opening it, I’d define the expense and the amount that would actually cover it; that simple boundary helps keep an urgent decision focused. With that purpose clear, it becomes easier to judge whether an advance is relevant or whether another route deserves a closer look.
A focused alternative to the usual payday routine
What separates this app from the familiar payday-loan mindset is the way it frames timing. Instead of assuming that the user is only a few days from receiving wages, CoverMe is built around the possibility that payday may be much farther away. That makes it more relevant to people dealing with irregular income, delayed pay, or an expense that lands at an inconvenient point in the pay cycle.
In my experience, the most useful way to approach the app is as a screening tool for a specific cash-flow problem. I would open it with one question in mind: “What expense am I trying to cover, and how will I handle the repayment?” That question keeps the app in its proper role. It is not a replacement for income, and it should not be treated as extra spending money simply because the application makes access feel immediate.
The store summary positions it as better than typical cash advances, but I would interpret that carefully. The meaningful comparison is not whether it sounds more convenient. The real comparison is whether its terms, repayment expectations, eligibility process, and total cost fit your situation better than other available options. Those details matter more than the speed of the first screen or the confidence of the wording.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Where the app can be genuinely useful
Imagine a household whose car needs an urgent repair so one person can get to work, while the next regular income is still several weeks away. A conventional payday product may be poorly matched to that timeline, especially if repayment is expected almost immediately. CoverMe is more relevant to that kind of gap because its basic proposition is built around a payday that is not close.
Another realistic case is a freelancer waiting for an invoice to clear. The person may know that money is coming but still face groceries, transport, or a utility bill before the payment arrives. In that situation, I would use the app to investigate whether an advance is practical, then compare the obligation with the expected income. The important step is writing down the repayment date and amount before accepting anything, rather than relying on memory.
A less obvious use is as a planning checkpoint for irregular earners. Someone with variable weekly income can look at a proposed advance and test it against a low-income period, not an optimistic one. If the plan only works when every upcoming shift or invoice arrives on time, it is too fragile. This is one of the strongest habits I would recommend to anyone considering the app.
What I would check before accepting an advance
The first check is the complete repayment obligation. I would not stop at the amount that reaches my account. I would look for the total amount due, the timing, any applicable charges, and what happens if the expected income arrives late. A cash advance can appear manageable when viewed as a single deposit but become difficult once it is placed beside rent, food, transport, and existing commitments.
The second check is whether the app is solving a one-off timing problem or hiding a recurring shortfall. If the same expense has caused a problem repeatedly, another advance may only move the pressure forward. In that case, a conversation with the bill provider, a payment arrangement, a local assistance service, or a trusted banking option may be more suitable than another short-term obligation.
The third check is privacy and account comfort. Before proceeding with any financial application, I would read every permission and authorization screen closely and avoid rushing through them. I would also make sure I am using the official store version and a secure connection. These are not dramatic steps, but financial apps deserve more caution than a casual utility download.
Finally, I would save the important confirmation details somewhere I can find them. A screenshot or written note of the repayment schedule can prevent the common mistake of remembering only the amount received. The app may make the application process straightforward, but the user remains responsible for tracking the resulting commitment.
The experience is approachable, but convenience has a downside
CoverMe’s free download removes an initial barrier, and the Everyone content rating makes it easy for a broad audience to find. The current version is 1.6.3, and the app supports Android 7.0 or later, so people using older but still common Android devices may be able to try it without upgrading their phone. Those details make it accessible, although compatibility alone does not tell me whether the financial offer will suit a particular user.
The strongest practical advantage is concentration. Instead of opening a general banking app and searching through unrelated tools, a user can focus on the cash-advance question. That is valuable when an expense is urgent and attention is limited. I also like that the concept is understandable without requiring the user to learn a complicated investment or budgeting system first.
There is a trade-off, though. A focused app can encourage tunnel vision. Once I open it because I need money, I may be tempted to judge the option by whether it solves today’s problem rather than whether it creates a larger problem next month. I would therefore treat the app’s simplicity as a reason to slow down, not a reason to skip the numbers.
The meaningful weakness: access is not the same as affordability
The main weakness is not necessarily a missing button or a confusing screen. It is the emotional effect of fast financial access. When money is tight, a clean process can make an advance feel like a normal purchase. It is not. The user is exchanging future cash flow for present relief, and that trade can be expensive or stressful if the repayment plan is not realistic.
This is also where CoverMe may be less suitable than a different alternative. If I only need a small amount for a very short period and already have a low-cost overdraft or a trusted bank feature with clearly understood terms, I would compare that option first. If the expense is a recurring necessity, I would look for a longer-term budget solution. If the situation involves serious debt, I would prefer qualified financial guidance or a nonprofit support service over repeatedly applying for advances.
People with unpredictable income should be especially careful. The app’s appeal may be strongest when payday is distant, but distance also means more opportunities for something to go wrong before repayment: a delayed invoice, fewer work hours, or another urgent bill. I would only consider an advance if I had a conservative repayment plan that remained workable after allowing for ordinary surprises.
I would also avoid assuming that a high user rating proves that every offer is favorable. Around 2.1 thousand written reviews and a strong average suggest that many people have had a satisfactory experience with the app, but personal affordability cannot be measured by popularity. Reviews can tell me whether people find an app usable; they cannot decide whether a particular financial commitment is wise for my income.
Who should consider it, and who should skip it
I see CoverMe as a reasonable app to investigate for an adult who has a defined, urgent expense, understands the repayment obligation, and expects a dependable source of income later. It may be particularly relevant to workers whose pay schedule does not line up neatly with their bills, provided they do not confuse a delayed payday with guaranteed spare money.
It can also suit someone who wants to compare a cash-advance route with a traditional payday product rather than accepting the first option found through a search engine. The app’s value is highest when it becomes one step in a comparison process. I would check the terms, compare the total cost with alternatives, and decide only after considering what remains in my account after repayment.
I would skip it if I was already using advances to cover previous advances, if my income date was uncertain, or if I could not explain how repayment would fit alongside essential bills. I would also avoid it for discretionary purchases. A delayed concert ticket or an impulse buy is not the same as a necessary repair or a basic household expense, and borrowing for wants quickly turns a temporary tool into a habit.
Users who want a full budgeting system, savings goals, spending categories, or investment tracking should look elsewhere. CoverMe’s identity is much narrower: it addresses access to cash around a delayed payday. A bank account app may be better for viewing balances, while a dedicated budget app may be better for finding the reason a cash shortage keeps happening. Choosing the right category matters as much as choosing the right provider.
Practical habits that make the decision safer
I would begin by calculating the gap rather than choosing an amount based on the maximum available. If the bill is smaller than the proposed advance, taking extra cash creates extra repayment pressure without solving an additional need. Borrowing only what the specific situation requires is a simple but important discipline.
Next, I would create a short cash-flow calendar. I would list the expected income, the repayment date, rent, utilities, food, transport, and any automatic payments. Then I would test the plan against a modest delay in income. If that small disruption makes the repayment impossible, I would treat the advance as too risky.
I would also read the final confirmation page slowly, even if I had already reviewed earlier screens. Financial applications can present the most important details near the point of acceptance. I would check the amount received against the amount owed and keep the confirmation for my records. If a term is unclear, I would not guess; I would seek clarification before agreeing.
One useful boundary is to decide in advance what would make me cancel the application. For example, an unexpected charge, a repayment date that collides with essential bills, or an obligation I cannot explain in plain language would all be reasons to stop. Setting that boundary before feeling rushed is easier than setting it after the money is already on the way.
My verdict after weighing the convenience against the risk
CoverMe is a focused finance app with a clear use case: examining an advance when the next payday is not close enough to solve an immediate cash problem. Its free availability, broad age classification, compatibility with Android 7.0 and later, and strong public reception make it approachable. DIONIS K has built something that speaks directly to a common frustration instead of burying the idea inside a much larger financial product.
My recommendation is conditional but positive. I would suggest trying it to a financially organized user who has a specific need, a dependable repayment source, and the patience to compare the full obligation with other options. I would not recommend treating it as a regular income supplement, an emergency fund, or an automatic answer to repeated shortages.
The app’s best quality is its relevance to people whose payday is genuinely far away. Its biggest risk is that the same convenience can make future income feel available before it has arrived. Used as a careful comparison and planning step, CoverMe can be a practical short-term option; used casually, it can postpone rather than solve the underlying problem.
For me, that is the deciding point. I would keep it in mind for a defined cash-flow emergency, but I would open my budget first, compare alternatives second, and accept an advance only when the repayment plan is as clear as the immediate need.
Frequently Asked Questions
01What is CoverMe - Instant Cash Advance, and how does it work?
CoverMe - Instant Cash Advance is a financial app designed to help eligible users request short-term access to money before their regular payday. After creating an account, you may need to provide personal, employment, income, and banking information. The app reviews your details and displays available options, fees, repayment terms, and delivery estimates before you decide whether to proceed. Availability and approval are not guaranteed.
02Who can use CoverMe, and what information is required to apply?
Eligibility can depend on factors such as your age, location, identity, income, employment status, and active bank account. During registration, CoverMe may request information needed to verify your identity and assess your application, including contact details, government-issued identification, employer or income information, and banking data. Requirements can change, so review the current conditions inside the app before submitting an application.
03How much does CoverMe cost, and are there any additional fees?
The total cost of using CoverMe depends on the advance amount, repayment schedule, transfer method, and the offer presented to you. Possible charges may include service fees, expedited transfer fees, subscription costs, or other disclosed charges. Carefully read the agreement and fee breakdown before accepting funds. An instant cash advance is not free money, and late or unsuccessful repayments may create additional financial consequences.
04How quickly can I receive money through CoverMe?
Delivery time varies according to your eligibility, application approval, bank processing, weekends, holidays, and the transfer option selected. Some users may see funds arrive quickly, while standard bank transfers can take longer. The app should show an estimated arrival time before confirmation, but this estimate is not always a guarantee. Make sure your linked bank account information is accurate to avoid delays.
05When must a CoverMe advance be repaid, and what happens if I cannot pay?
Repayment is generally scheduled according to the terms shown when you accept an advance, often around your next payday or another agreed date. Before using the service, confirm the repayment amount, date, and authorization method. If you expect difficulty repaying, contact CoverMe support as soon as possible and review its policies. Missed payments may result in fees, account restrictions, collection activity, or other financial effects.


